Economics
Polonius on superannuation
Our “one size fits all” superannuation scheme, with its compulsory 12 percent contribution rate, does not fit all, but it does a good job for the vast majority. There is no reason to demolish it by allowing early withdrawal.
Pauline Hanson and others on the populist right have raised the possibility of allowing people to withdraw money from their superannuation accounts to pay for housing.
You can follow an argument about early superannuation withdrawals on The Economy Stupid – One Nation wants to allow early access to super: is it a good idea?. Susan Thorp of Monash University puts a standard justification of compulsory superannuation, while Cameron Murray of Fresh Economic Thinking puts a counter argument.
There are several strains to that counter argument. One is about the apparent absurdity of people investing in financial assets, while borrowing from the same institutions to finance their mortgages, thus defying Polonius’ gratuitous advice “never a borrower or lender be” –- certainly not both at the same time. The only beneficiaries are those in the finance sector who take two lots of commission on the money’s round trip.
It’s an appealing argument, but it overlooks the difference between borrowing to finance housing, a secure asset, and investing in a growth asset, such as a portfolio of shares in a superannuation fund. It’s everyman’s (and everywoman’s) way of getting into leveraged investment in a reasonably secure way. That is, provided fees and commissions are reasonable, superannuation funds are well-managed, and housing is not ridiculously overpriced.
Another argument is that superannuation is our money and we can choose what to save and what to spend.
That principle generally guides our lives, but we don’t exercise that choice rationally. We know we should save for retirement, we want to save for retirement, but we know we don’t. As behavioural economists point out, our behaviour is guided by a version of Saint Augustine’s prayer “Lord, make me a saver, but not yet”. (The economists’ term for this behaviour is “hyperbolic discounting”). Thomas Schelling put it in utilitarian terms, when he posited the idea of a 20-year old “me”, imagining a 60-year old “me” feeling grateful that someone forced “me” back 40 years ago into saving for retirement. We’re quite pleased to have a trusted and accountable party enforcing that deal on us.
Then there is the argument, based on what looks like empiricism, that 40 years of compulsory superannuation has failed to keep people “off the pension”.
In a Pearls and Irritations article – Both opposition parties have superannuation in their sights – Saul Eslake presents the simple mathematics debunking that argument. Over that 40 years there has been a big growth in the proportion of the Australian population aged 65 and over, and the percentage receiving the age pension has fallen from about 73 percent in 2005 to 55 percent now. We now stand out among OECD countries as having very low public spending on age pensions.
Murray also sees a degree of intergenerational inequity, in that many older people enjoy a much better lifestyle than younger people, and better than they had experienced in their own younger years.
There is substance to this observation, but in part it is a transient problem in that it results from a period when there were excessively generous tax concessions for contributing to superannuation and the continuation of many defined-benefit schemes. It also relates to tax concessions which exempt the earnings from the first $3 million of one’s superannuation from income tax. The government is making glacially slow pace towards applying the same tax provisions to workers and retirees, but has made a first step in making a $1000 tax deduction available only to those receiving PAYG income.
Thorp explains that we do have provisions for withdrawal from superannuation for compassionate grounds and for medical emergencies, but these are used mainly by older people, who may have accumulated a large superannuation balance. A withdrawal (or an exemption from contribution) at a younger age when people are buying houses comes with a large opportunity cost in terms of the compounding gains never achieved. She points out that many such withdrawals are for dentistry. That’s really a comment on a long-standing gap in Medicare, rather than a problem with superannuation.
Then there is the problem of injecting more funds into housing at a time when supply is constrained. As with the government’s ill-advised, but popular, 5 percent deposit scheme, it would add to funds for housing without increasing supply, thereby contributing to house price inflation. Also it would add to the money supply generally, at a time when the Reserve Bank is trying to dampen inflationary expectations, as Eslake explains. Financial journalist Victoria Devine covers the same point in her article People take the money and run: the pitfalls of early super access. Under the early withdrawal proposals there may be a condition that it be tied to housing, but it’s still an injection of funds into the economy. When, during the Covid pandemic, people were allowed to withdraw up to $20 000 from superannuation, there was a much larger than expected withdrawal, contributing to the wave of post-pandemic inflation.
Where Murray is right is in his assertion that compulsory superannuation at 12 percent may be forcing people into contributing more than they need. That is possible. In fact someone retiring around now who had been contributing 9 or 12 percent of their income for 40 years would have a sound balance, capable of financing around 70 percent of their pre-retirement income. But that’s over a period that includes a commodity boom and a strongly rising share market. There is no guarantee that such conditions will prevail in the future. In setting contributions there also have to be assumptions about life expectancy, which is still trending upwards.
The problem facing policymakers is to find a balance between a rigid one-size-fits-all set of regulations, and a more flexible set designed to deal with different people’s circumstances, that add complexity and opportunities for gaming the scheme’s provisions.
Interest rates – will we follow the Fed?
Australia will probably follow the US Fed in raising interest rates, but that won’t do anything to ease inflationary pressures and will add to the attraction of simplistic policy put forward by populist parties.
If you have a good understanding of how the world works, but have never been subjected to the magic of macroeconomic theory, you would feel rather confused if you were trying to follow Reserve Bank Deputy Governor Andrew Hauser on the ABC’s 730 program, explaining why the RBA is likely to raise interest rates.
He explains that the economy is doing “quite well” with modest but sustainable growth, that employment is growing and unemployment is low, that real household incomes are growing strongly, and that there has been substantial private investment.
That all suggests we are on the right track, but he goes on to say we have one big problem, inflation, which is putting pressure on the Bank to raise interest rates, either at its next meeting on 28 September, or later in the year.
He goes on to explain the source of inflation, including oil prices, the artificial intelligence boom driving investment in data centres, and supply problems, all pushing up the CPI. In fact since his appearance the oil price has risen further, resulting from the Houthis blocking the Red Sea.
Australians don’t have much control over any of those conditions. They may be driving higher prices, but it’s not a problem of excess demand feeding a wage-price spiral, calling for a reduction in money supply. In fact he mentions that consumer confidence is low. And he acknowledges that in one important area, housing, prices are falling – at last.
It’s all about that indicator, the CPI.
Some Australians, including those who have taken on more mortgage debt than they can handle, are having a hard time, and they will suffer further stress from a rise in interest rates. In fact, they would benefit from a modest bout of inflation with nominal price rises offset by nominal wage rises, because that would reduce the burden of their housing loans. That was the way inflation reduced private debt in the postwar boom and in the 1970s.
But because one inflation indicator, the CPI, which has an inherent bias to overstate inflation, is outside an arbitrary two to three percent range, interest rates have to rise.
Hauser, like many other economists, acknowledges the problem of our poor labour productivity. The usual way to improve labour productivity is to increase the capital intensity of the economy, but rising interest rates – particularly the expectation of rising rates – suppresses investment by raising the cost of capital.
The main way increasing interest rates works is through suppressing demand. Higher oil prices will do that for us as they flow through to pump prices. Most of that extra $1 or so a litre goes to the oil producers and the refinery owners. It doesn’t flow back into the Australian economy. Higher pump prices are already doing what higher interest rates will do. So why make it even worse by raising rates?
That is not a personal criticism of Hauser. His economic explanation would get an A+ mark at a university, and his 19-minute explanation is much more informative than those insipid cut-and-paste press releases the Reserve Bank issues after board meetings.
Rather, it’s about the way we have allowed an abstract economic model to determine a crucial aspect of economic policy. As Michael Janda explains in his post higher interest rates won’t deal with the drivers of inflation.
Not just here in Australia, but around the world, policymakers seem to be entrapped in an economic model that may have had some connection to reality in the past but that has been demonstrably wrong ever since the 2008 global financial crisis. In fact our high level of personal indebtedness arises largely from the absurdly low interest rates in the decade following the GFC – a point the RBA never acknowledges.
The damage inflicted by that period of low interest rates is one of the main points in a post by Gareth Hutchens about the work of British economist Charles Goodhart, who warns that the next few decades will be very difficult, because the economic models that have been guiding our policymakers are no longer delivering benefits for all, particularly young people.
Missing from those established macroeconomic models is any consideration of the political consequences of monetary policy. Mortgage stress is driving voters to populist parties, whose policies, if implemented, could do far more enduring economic damage than a few years of modest inflation could ever do. Or mortgage stress could result in the election of a hard right government, imposing austerity and a “small government” agenda, inflicting on Australia what the Thatcher government inflicted on the UK.
We need a better model.
The ambassador returns from the imperial capital
Kevin Rudd has returned to Australia, advocating an industry policy to strengthen our resilience.
Kevin Rudd’s address to the National Press Club has some of the flavour of the local lad who has returned home after a long time – too long perhaps – in the imperial capital. By the same token, however, that vantage point has allowed him to see Australia from the outside. His speech – The complacent country – has echoes of Donald Horne’s warning about the lucky country, prompting him to call for “a radical change in our national mindset”.
Some would disagree with his idea that we have become complacent; our mood may be better described as restive. But many would go along with his call for a change in our mindset. He urges us to develop our own terms of engagement with the world, to be the creator of new technologies and not just the users, to move up the value chain to capture value in processing our mineral resources, to become price-setters rather than price-takers, and generally to build a more resilient economy.
Such exhortations go back to colonial times, but they differ in their specific content, which Rudd covers in two broad themes.
The first is about defence security and sovereignty, not only in hardware, but also in cyber security, with particular reference to artificial intelligence. We are living in a world where China is setting a new order, moving in where America has moved out, and is re-shaping that order in its own interests.
Most of the Q&A part of the session is about security-related issues, such as Australia’s possible response to a Chinese takeover of Taiwan. Rudd’s responses are cautious and hedged, as if he is still the ambassador to the US, attentive to a brief prepared by Foreign Affairs.
His other theme is about the need for an industry policy, and here is where he departs from established policy orthodoxy. He knows that Treasury considers anything that hints at industry policy, particularly sector-specific policy, to be heresy.
Undeterred he names seven sectors – artificial intelligence, biotechnology, renewable energy, critical minerals, defence industry, automotive industry, and finance – that should be subject to sectoral-based industry policy. These are not just specialties we drift in to: rather, they should be deliberately chosen. Each industry plan would be guided by a “tailored set of tax, regulatory, policy and permitting incentives – commonwealth, state and local”. It’s reminiscent of his time as prime minister when he said he didn’t want to be prime minister of a country that doesn’t make things anymore.
Bernard Keane, writing in Crikey, sees Rudd’s speech as “another step in the rehabilitation of protection”, although at no point does Rudd call for tariffs or import quotas: industry policy does not have to involve protection. But Keane quite understands why protectionism has come back into fashion, and he blames the corporate sector:
How did we get here? Like many aspects of free market economics now being abandoned, big corporations can take a bow for their role in turning voters against free trade. Whatever the initial benefits of freer trade and globalisation of supply chains, large corporations worked overtime to ensure workers and consumers saw as few of those benefits as possible, while those corporations drove prices up, pushed wages down and systematically rorted the tax system, while spending billions influencing governments to look after them.
Listening to Rudd one may feel that he is talking to Australians in the late 1930s, when a succession of conservative governments had left the country economically run down and unprepared for a looming threat. Maybe it’s timely that he’s repeating that message.
Data centres explained
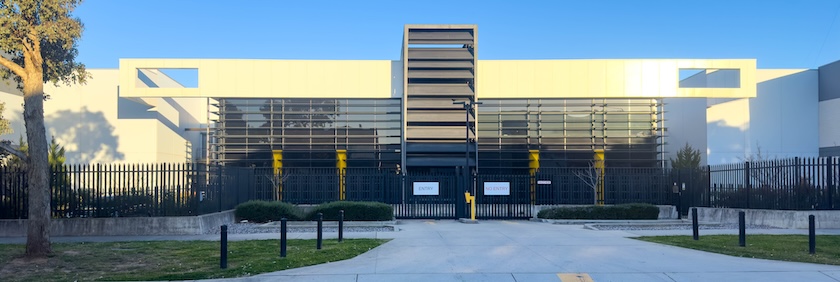
CDC’s big shed in Canberra
They’re just big storage sheds, without much ongoing benefit for Australia.
Much of the increase in recorded capital expenditure in recent times is attributed to the construction of data centres. What do we know about them?
In the most recent Australia Institute What’s the point? podcast Richard Denniss explains what the lay person needs to know about data centres.
If you have seen them and believe they look like great big sheds, you’re not wrong, because for the most part that’s essentially what they are – big storage sheds where stuff is stored. That’s “the cloud”, where, if you use certain programs, your data is stored. Think of a Coles or Woolworths distribution centre warehouse, replace the trucks coming in ad out laden with produce with fibre optic cables carrying ones and zeros, and replace the racks of supermarket produce with computers with terabytes of storage capacity, and you have a data centre. And like warehouses they don’t employ many people – if you’re driving past one, notice how small their car parks are.
But unlike the supermarket distribution warehouse they require a lot of electricity and water, because all those computers need power to operate, and must be kept cool. (You may note that your phone or computer gets hot when it is working hard.)
They don’t sound like very exciting ventures, but the government likes them because they contribute to national accounts figures on private sector investment. That impresses financial journalists and the counters opposition parties’ claim that this dreadful Labor government is so incompetent and so given to socialism that no private company wants to invest here. As Denniss explains, they provide jobs in the construction phase, but not much ongoing employment. Depending on the skills of their accountants they may pay a little income tax in time, after they have depreciated investment in their sheds, but any dividends are likely to go overseas.
The Queensland and Northern Territory governments, keen to find uses for their fossil fuels and indifferent about climate change, like data centres. Anthropic has just signed an agreement for a $32 billion data centre in Queensland’s Western Downs, about 200 km northwest of Brisbane. At peak it will draw about 2 GW of electricity, probably using all the capacity of the nearby 750 MW Kogan Creek coal-fired power station, and some more from smaller gas-fired stations in the region. Unlike the old coal-fired stations in New South Wales and Victoria, which can operate only with expensive life support, Queensland’s coal-fired stations are newer: Kogan Creek is only 20 years old.
Reform wasn’t meant to be easy
The path to economic reform is long and tortuous, and is rarely in one direction: there are often reversals on the way.
Beth Webster of the University of Melbourne has a Conversation contribution Reform wasn’t meant to be easy. She takes us through three case studies – the 30-year battle for Medicare, the shorter but difficult struggle to develop a system of child support when parents divorce, and the transformation of Australia from a country with some of the world’s highest tariffs to one of the world’s most open economies.
The common element is the dedication of people – politicians, public servants, academics, staff of non-government organisations – working tirelessly to push for reform, undeterred by setbacks, modest enough to allow others to take credit for achievements, and patient enough to realize that reform may take many years.
On that last point I disagree with her assessment that Medicare took 30 years: 90 years on from the first proposals for a universal health scheme Medicare is still not fully implemented. Dentistry is still excluded, specialist services are in short supply, and we still have the burden of private health insurance misallocating resources and making health care more expensive than it need be. That disagreement strengthens her point about the long path to reform.
Sometimes resistance comes not from those with a financial vested interest, but from those who have learned to live with current arrangements and cannot envisage anything different. That seems to have been the case with reforms to ensure children are given assured care after their parents divorce.
Sometimes, as with the case of Medicare, reform involves confronting vested interests, while at other times reform involves bringing vested interests on side, as was the case with industry policy. Webster’s point is that there is no one successful pattern.
She concludes with two challenges for reform – housing affordability and wealth inequality – that promise to be no less difficult than the past reforms about which she writes.